Therapy and Insurance: What You Need to Know Before Starting Therapy
If you're thinking about starting therapy and want to use your insurance, you might be struggling to understand what this entails — do the therapists you are considering take your insurance? What does that mean? How much will therapy actually cost?
Insurance is confusing for most of us. Even as a provider who has been in the field for over ten years, I still come across insurance situations that I’ve never seen before. So you certainly aren’t alone in being confused. But if you can start to understand some of the common insurance-related terms and have answers to some basic questions, you are in a much better position to be empowered as you try to understand your plan and connect with a therapist.
Here are some of the questions people ask me most often.
Why is insurance so confusing?
Every insurance company has its own rules, and even people with the same insurance company can have completely different benefits depending on the plan they have.
For example, one question I often receive from new potential clients is, “I have BCBS for insurance. How much will sessions with you be?” Unfortunately, based on only that information I cannot give a helpful answer. I have seen costs range from $0 to $150 per session just within BCBS plans, and the same range applies for all other health plans too. Of course, when a new client decides to work with me or a current client changes their plan, I reach out to their insurance company to find out what exactly the costs would be. So it is definitely a realistic expectation that you will start sessions knowing how much they cost. It just is not as straightforward as knowing who your insurance carrier is.
In addition, info we receive from the insurance company is sometimes incorrect. That's one reason therapists sometimes encourage clients to call their insurance company themselves. It isn't because we're passing the responsibility back to you. It's because your insurance company is ultimately the only one that can tell you exactly how your specific plan works, and having two people check (both you and I) helps to ensure that we get the most accurate information.
What does "in-network" actually mean?
This is probably one of the most common questions I hear.
When a therapist is in-network, it means they've signed a contract with a particular insurance company.
That contract sets things like how much the therapist will be paid for each session, what documentation is required, and other rules both sides agree to follow.
If a therapist is out-of-network, it simply means they don't have that contract.
Some insurance plans will still help pay for out-of-network therapy. Others won't.
Unfortunately, there isn't a universal answer because every plan is a little different.
Why doesn't every therapist take insurance?
I completely understand why people wonder this. From the outside, it can seem like a simple decision. If a therapist wants to make therapy accessible, why wouldn't they just accept every insurance plan?
The reality is usually more complicated than that. One thing people don't always realize is that therapists don't have one relationship with "insurance." We have separate contracts with each insurance company.
That means a therapist might be in-network with Blue Cross but not Aetna. Or with Aetna but not United Healthcare. From the outside, that can seem random, but there are usually practical reasons behind those decisions.
Every insurance company reimburses therapists differently. They all have different credentialing processes, documentation requirements, billing systems, and policies. Some also are known for less ethical practices, which some therapists do not want to support and enable by signing contracts with them.
Another factor that people don't always know about is that insurance companies require therapists to diagnose clients and document that therapy is medically necessary. For many people, that's completely appropriate. But some therapists prefer not to work within that system for every client they see.
None of this means insurance is "bad," and it certainly doesn't mean therapists who accept insurance or don't accept insurance care more or less about their clients.
They are just different ways of running a practice. For me, I have mixed opinions about taking and not taking insurance. There are pros and cons to taking insurance and having a private pay only practice. I balance this by only contracting with insurance companies that have the most ethical practices, rules, and expectations in the states in which I am licensed. It is not perfect, but for the moment in my practice it seems like the best way to balance making therapy accessible while minimizing my engagement with insurance companies that have the most harmful practices.
What's the difference between a deductible, copay, and coinsurance?
These are probably the three terms that cause the most confusion.
Premium
Let's start with one that actually has nothing to do with your therapy session itself.
Your premium is what you pay every month to have health insurance. You pay it whether or not you use your insurance.
Deductible
A deductible is the amount you may need to pay for healthcare before your insurance starts paying a larger share of the cost.
Let's say your deductible is $2,000.
If you haven't met any of it yet, you may be responsible for paying the full cost of your therapy sessions until you've reached that amount. Or, you may not be: Some plans apply deductibles to therapy. Others don't.
That's why it's always worth checking your specific benefits.
Copay
A copay is much simpler.
It's a fixed amount you pay each session.
For example, every therapy appointment might cost you $30 regardless of what your therapist charges.
Coinsurance
Coinsurance works a little differently.
Instead of paying a fixed dollar amount, you pay a percentage.
For example, after you've met your deductible, your insurance might pay 80% of the session and you pay the remaining 20%.
Out-of-pocket maximum
This one often gets overlooked.
Your out-of-pocket maximum is essentially the most you'll pay for covered healthcare during your plan year.
Once you've reached that amount, your insurance generally pays the full cost of covered services for the rest of the year.
Who is the subscriber? What is a dependent?
These are actually two of the easier terms.
The subscriber is simply the person who owns the insurance policy. Often the subscriber is the person who has their insurance plan through their job or purchases it through the marketplace.
The dependent is someone who is covered under that person's plan.
For example, if you're on a parent's insurance until age 26, your parent is the subscriber and you are the dependent.
What questions should I ask my insurance company?
I know calling your insurance company probably isn't anyone's idea of a good time.
But spending ten or fifteen minutes asking a few questions before your first appointment can save you a lot of confusion later.
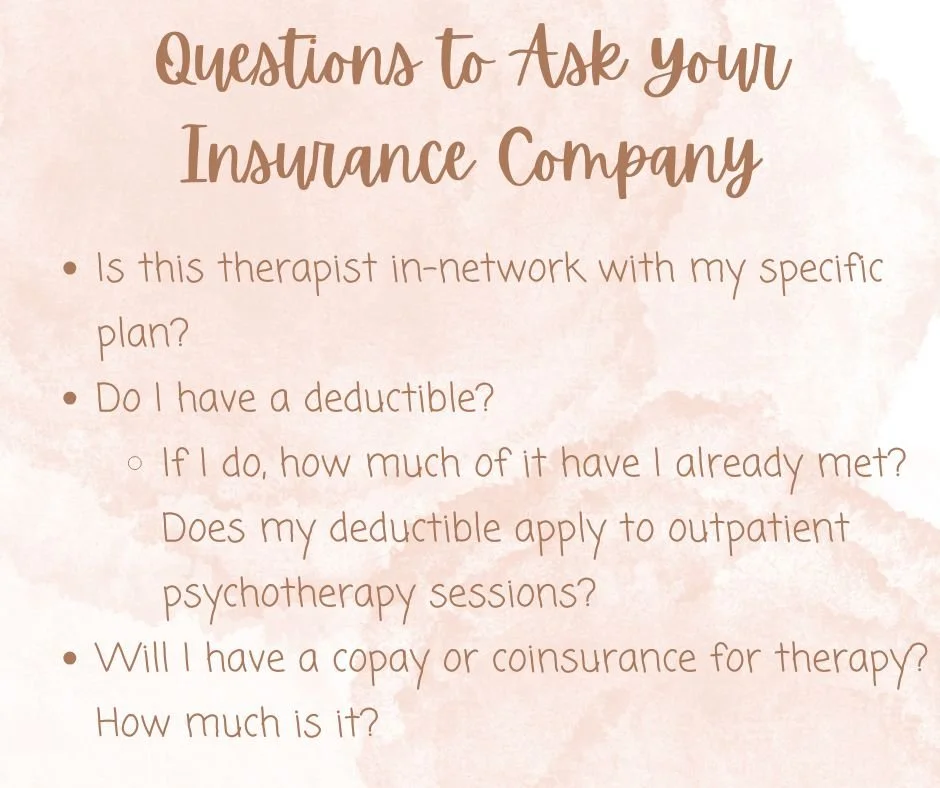
Here are a few questions that are worth asking:
Is this therapist in-network with my specific plan?
Do I have a deductible?
If I do, how much of it have I already met? Does my deductible apply to outpatient psychotherapy sessions?
Will I have a copay or coinsurance for therapy? How much is it?
I also recommend writing down the name of the representative you spoke with and, if possible, asking for a reference number for the call. While insurance companies generally provide accurate information, mistakes do happen. Having a record of the conversation can be helpful if questions come up later.
A Final Thought
If you've made it this far, congratulations. It’s a lot of info!
Insurance can feel like a maze sometimes, especially when you're already trying to take the vulnerable step of finding a therapist.
The good news is that you don't have to understand every part of your insurance coverage before you reach out for help.
If you give your insurance info to your therapist, they should be happy to answer questions about how billing works in their practice, and help you understand what to expect as much as they can. They may also be able to suggest questions to ask your insurance company and ways to advocate for your needs if needed.
And if you're ever unsure, it's okay to ask. Chances are, you're asking a question that many other people have had too.